Headlines about Dubai property swing between record-breaking and slowing down. Neither helps you make a decision. Here is what the registered data shows for Q3 2026, and how I read it for clients buying in the AED 2M-plus segment.
1. Volumes are down, prices are broadly holding
- 32,788 residential sales were registered with the Dubai Land Department in Q3 2026, 35.7% fewer than a year earlier and 2.2% fewer than in Q2 (DLD data via Cevitas).
- The median price was AED 1,687 per sq ft, only 1.3% lower year on year.
- Off-plan was 73.6% of transactions by number but 59% of sales value (DXB Interact data reported by AGBI).
Fewer deals with stable prices is a sign of a market that is pausing rather than breaking. Sellers are not being forced to discount across the board. Buyers simply have more time and more negotiating room.
2. Villas are outperforming apartments
Villa and townhouse prices rose 9.9% per sq ft year on year, while apartments fell 2.6% (DLD via Cevitas). Demand from end-user families for space in established communities has not weakened. This is why ready family villas such as Sidra in Dubai Hills Estate feature in my current portfolio.
3. The off-plan premium is narrowing
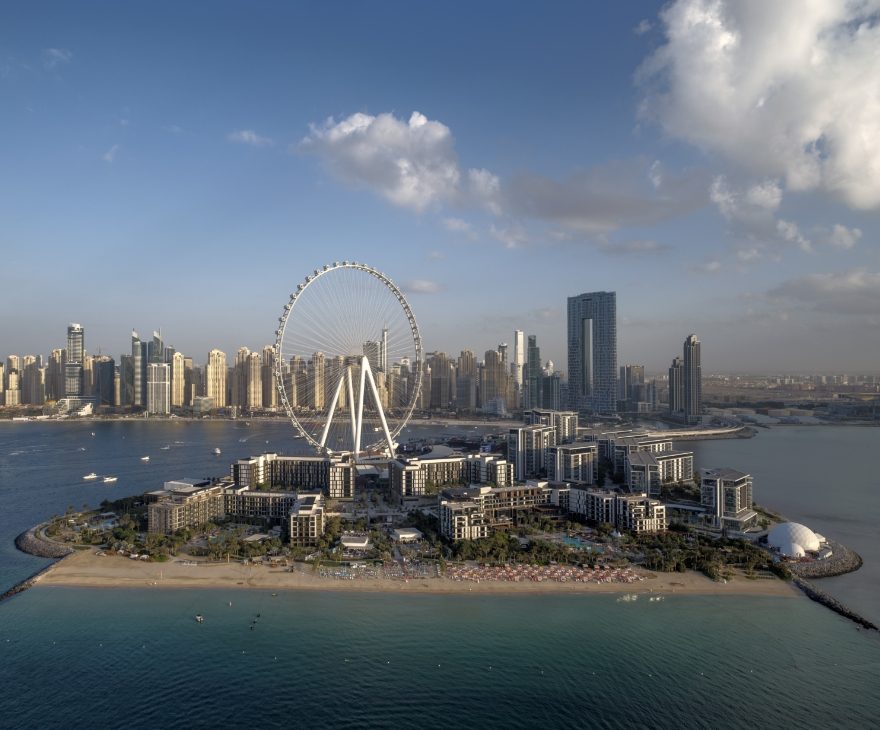
The median off-plan apartment fell nearly 5% year on year to AED 1,703 per sq ft in September, while the median resale apartment rose to AED 1,514 (AGBI, from DLD data). The gap between new and completed stock narrowed by more than a third. For buyers, completed trophy assets such as Bluewaters Residences now look comparatively better value. Off-plan has to earn its place through the developer, the location and the payment plan.
4. Prime prices dipped for the first time since 2020
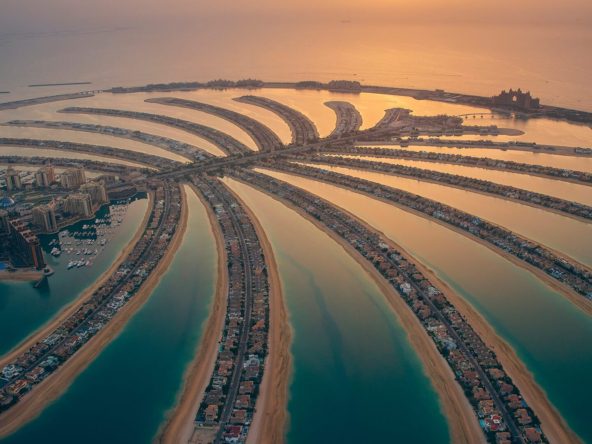
Knight Frank reports a 5% quarter-on-quarter decline across Dubai’s ten prime neighbourhoods in Q3, with Palm Jumeirah at AED 4,083 per sq ft after a 9.1% annual correction. Yet 412 homes above US$10 million sold in the first nine months of the year, against 357 a year earlier. Wealth is still arriving, and it is negotiating harder. That is the moment to secure the rarest stock, such as Solaya on Jumeirah 1.
What I am advising clients now
- Buy quality, not volume. Blue-chip developers, finished or near-finished communities and scarce waterfront land.
- Read the payment plan as closely as the price. Plans that leave more capital in your hands until handover, such as Soulever’s 50/50, reduce your exposure.
- Use the slower market to negotiate. In resale, documented, vacant-on-transfer units give you the strongest position.
Every client’s numbers are different. If you would like a view on a specific unit or community, I will prepare one with the registered data, not the brochure.
Properties mentioned in this article
- Sidra Villas, Dubai Hills Estate (Ready)
- Bluewaters Residences, Bluewaters Island by Meraas (Ready)
- Solaya, La Mer Jumeirah 1 by Meraas
- Soulever, Dubai Maritime City by BEYOND
For details on any of these properties, or a view on your own portfolio, get in touch.
Sources
- Cevitas Real Estate, Dubai real estate barometer, Q3 2026 (Dubai Land Department open data) (link)
- AGBI, Dubai's off-plan launch drought shows up in tumbling sales, October 2026 (DLD data via DXB Interact) (link)
- Knight Frank, 412 US$10 million+ homes sell in Dubai between Q1–Q3 2026, October 2026 (link)
This article is for information only and is not financial or investment advice. Figures are taken from the sources listed and may change.